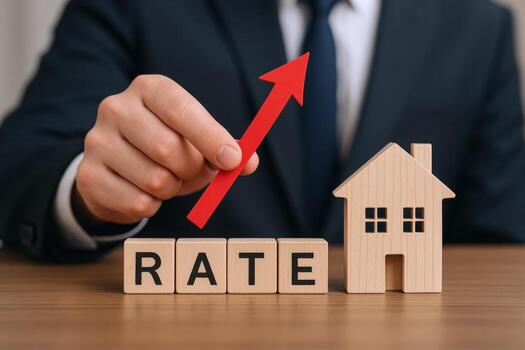
The South African Reserve Bank increased its benchmark repo rate by 25 basis points to 7% on Thursday. This significant move marks the first interest rate hike since May 2023, signaling a proactive stance by the central bank. The decision comes amidst rising inflation pressures within the South African economy, prompting monetary policymakers to act to stabilize prices. The adjustment in the repo rate is expected to have a ripple effect across various sectors, influencing borrowing costs and consumer spending patterns.
Inflationary Pressures Mount
Consumer price inflation in South Africa climbed to 4% in April, an increase from 3.1% recorded in March. This notable rise shows the growing inflationary environment and was primarily driven by several factors impacting household expenses. Contributing to the inflationary pressures were rising fuel prices, which directly affect transportation and logistics costs across the economy, subsequently impacting the price of goods and services. Additionally, municipal tariff hikes implemented by local authorities increased the cost of various essential services for consumers, adding to their financial burden. Increased electricity costs also played a significant role in pushing up the overall inflation rate, impacting both households and businesses, who face higher operational expenses. These combined factors indicate a broad base for the recent inflationary surge, extending beyond a single commodity or service. The central bank's decision to raise interest rates is a direct response to these persistent and widespread inflationary trends.
Impact on Homebuyers
The housing market is also feeling the effects of the broader economic climate. From January to April, deposit percentages for first-time homebuyers averaged 8.3% of the purchase price. During the same period, overall deposits across all homebuyers averaged 12.4%. These figures represent a decrease compared to a year earlier, when first-time homebuyers’ deposits stood at 9.9% and the overall average was 14.9%. This downward trend in deposit percentages suggests a shift in buyer behavior or market conditions.
Despite the lower deposit averages, financial institutions are actively offering various lending solutions to prospective buyers in an effort to maintain market activity. These include zero-deposit bonds, which significantly reduce the initial capital outlay required for a property purchase, making homeownership more accessible to some. Additionally, some lenders are providing cost-inclusive loans that cover up to 110% of the property's value, enabling borrowers to finance associated costs such as transfer duties and legal fees alongside the purchase price. These innovative lending options aim to mitigate some of the financial barriers faced by homebuyers in the current economic environment.
Broader Economic Context
Unemployment in South Africa has risen to 32.7%, according to data released by Statistics South Africa. This figure contributes to a challenging economic environment for the nation, noting persistent structural issues. The persistently high unemployment rate reflects ongoing challenges within the labor market and broader economic pressures, impacting consumer confidence and spending. While the South African Reserve Bank addresses inflation through its monetary policy decisions, the underlying unemployment figures indicate a significant hurdle for sustained economic recovery and stability. The elevated jobless rate impacts consumer spending power and overall economic growth prospects, presenting a complex challenge for policymakers as they navigate monetary policy decisions aimed at balancing inflation control with economic growth.
Expert Commentary
The South African Reserve Bank's decision has pushed the prime lending rate to 10.5%. This increase in the prime lending rate will directly affect the cost of borrowing for consumers and businesses, including those with variable-rate mortgages and other loans. Alongside this, actual deposit values experienced a notable decline for homebuyers, reflecting the evolving financial landscape. Data indicates that actual deposit values decreased by 14.8% for first-time homebuyers, suggesting a significant reduction in the upfront capital they are putting down. For all homebuyers collectively, the actual deposit values saw a larger decline of 16.8%, indicating a broader trend across the property market. These shifts reflect the evolving financial landscape for property transactions in the current economic climate, where both borrowing costs are rising and initial deposit requirements are changing.